
Buying as an investment? Here's how to assess rental demand, cash flow, and tenant quality before you commit to an income property in the GTA.
Assess Rental Demand First
Before buying an income property, confirm strong rental demand in the area. Look for proximity to employment hubs, transit, schools, and amenities that attract tenants. Check current rental listings on Realtor.ca, Rentals.ca, and Kijiji for your target neighbourhood — high listing volume with quick rentals signals demand. Low listings or long vacancy periods signal weak demand. Your agent can pull recently leased comparables to show actual rent rates and vacancy trends.
Calculate Realistic Cash Flow
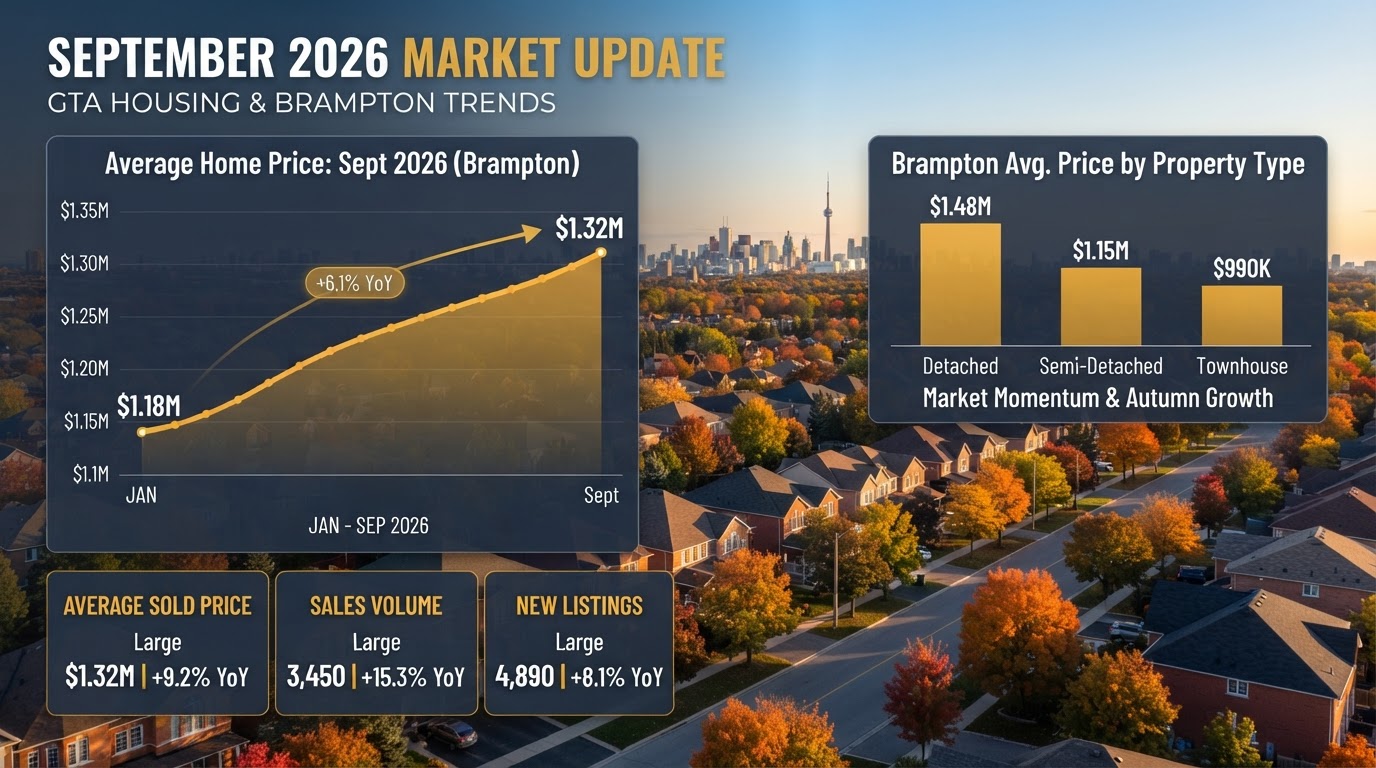
Cash flow = gross rent minus all expenses: mortgage payment, property tax, insurance, utilities (if you pay), maintenance (budget 1% of property value annually), property management (8–10% if used), and vacancy allowance (5% of gross rent). In Brampton, many properties run near break-even at current prices — positive cash flow usually requires a larger down payment, a legal second unit, or buying below market. Run this calculation before offering, not after. A property that doesn't cash-flow is a speculative bet, not an investment.
Cap Rate and Cash-on-Cash Return
Cap rate (net operating income ÷ property value) measures return regardless of financing — useful for comparing properties. Cash-on-cash return (annual cash flow ÷ cash invested) measures your return on the down payment — what you actually earn on your money. In the GTA, cap rates typically run 3%–5% for condos and 4%–6% for properties with second units. Know both metrics for any property you're considering. A good agent and your accountant can calculate these precisely.
Legal Second Units: The Cash-Flow Multiplier
A legal second unit (basement apartment) can transform a property's cash flow. In Brampton, a detached home with a legal basement suite can generate $3,800–$5,000+ in combined rents versus $3,000–$3,800 for the main house alone. Verify the unit is legal (permits, egress, fire separation, ESA certificate) before counting the income — illegal units risk enforcement, insurance denial, and financing issues. Properties with legal second units are among the GTA's strongest cash-flow investments.
Tenant Quality and Screening
Tenant quality determines your experience as a landlord. Screen thoroughly: credit check, employment verification, income (2.5–3× rent), previous landlord references, and a completed application. A good tenant pays on time and cares for the property; a bad tenant costs you arrears, damage, and LTB headaches. Ontario's Residential Tenancies Act favours tenants in disputes, so prevention through screening is essential. Consider a property manager if you don't want to handle screening and management yourself.
Financing and Insurance for Investors
Investor mortgages differ from owner-occupied: lenders typically require 20% down for a rental (versus 5% for owner-occupied), charge slightly higher rates, and assess the property's rental income in qualification. Insurance for rental properties (landlord insurance) costs more than homeowner insurance and must cover tenant-related risks. Factor these into your cash-flow calculation. A mortgage broker experienced with investor financing is invaluable — they know which lenders favour investment properties.
The Bottom Line
Assess rental demand, calculate realistic cash flow, understand cap rate and cash-on-cash return, consider legal second units, screen tenants rigorously, and arrange investor financing and insurance. Book a free investor consultation and I'll run a complete cash-flow analysis on any property you're considering.