The Bank of Canada's next rate decision is approaching. Here is a data-driven look at what a hold, cut, or hike means for GTA mortgage rates, buyer demand, and Brampton home prices this fall.
What to Expect at the Next BOC Rate Decision
The Bank of Canada's next interest rate announcement is the single most watched event for Canadian mortgage holders and prospective home buyers. After a steady summer of holding the overnight rate, markets are pricing in a meaningful probability of a further cut as inflation eases toward the 2% target and economic growth slows under the weight of renewed trade tensions. For the GTA housing market, even a 25-basis-point move can shift borrowing power by tens of thousands of dollars — which is why every buyer, seller, and investor should understand the scenarios before the announcement drops.
Where Rates Sit Right Now
As of early September 2026, the Bank of Canada's overnight target rate sits at a level that has brought five-year fixed mortgage rates down to roughly the 4.2%–4.6% range — a far cry from the 5.5%+ peaks of 2023 but not yet at the historic lows of the pre-pandemic era. Variable rates track the prime rate, which moves in lockstep with the BOC's overnight rate. The key insight: variable-rate holders feel every BOC move immediately, while fixed-rate holders are locked in until renewal. With roughly 60% of outstanding Canadian mortgages up for renewal in 2026–2027, the next decision reverberates through millions of household budgets.
Scenario 1: A 25-Point Cut (Most Likely)
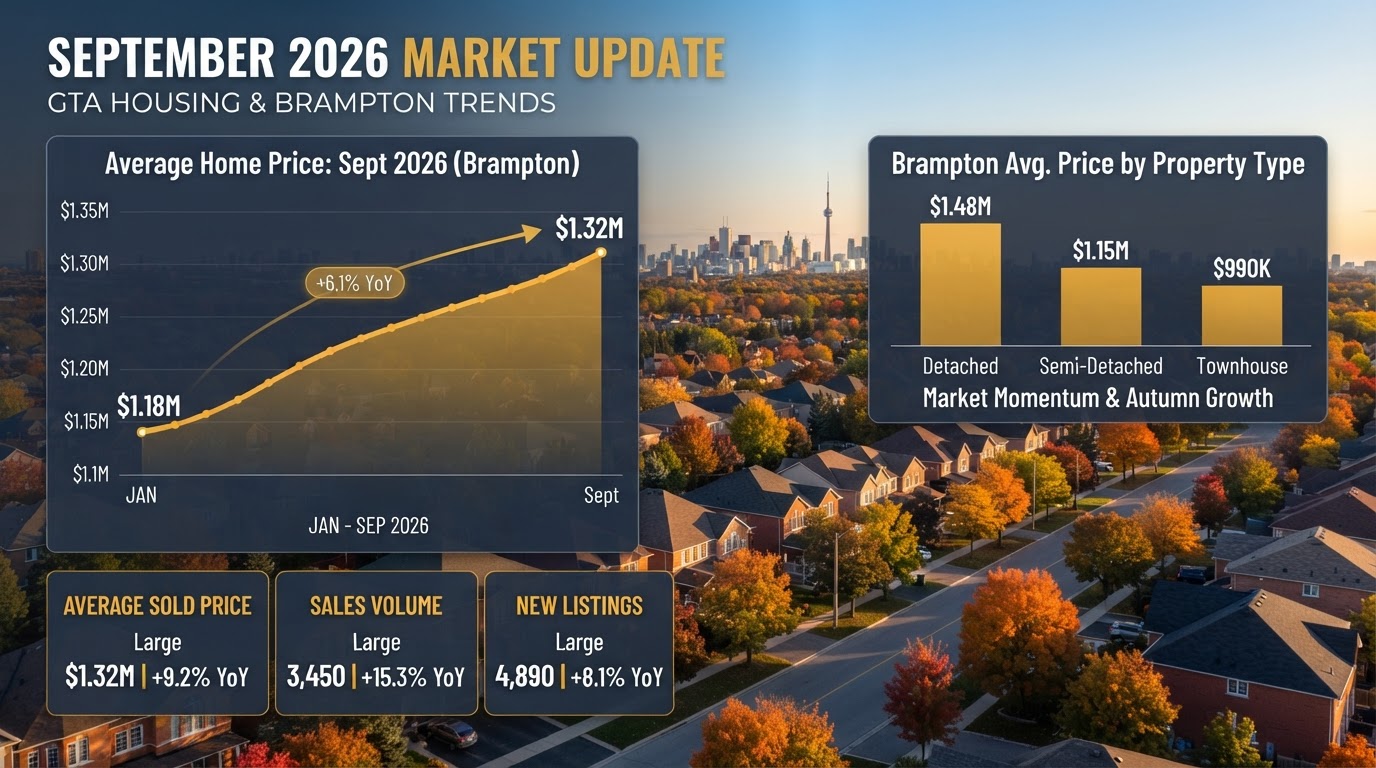
If the Bank cuts by 25 basis points, expect an immediate drop in prime rate and variable mortgage payments, plus a modest rally in five-year bond yields as markets bet on further easing. For GTA buyers, a cut translates directly into more borrowing power: at a 4.2% five-year fixed, a household earning $130,000 with a 20% down payment qualifies for roughly $740,000 — versus $720,000 at 4.4%. Brampton detached homes averaging $1.18M become marginally more affordable for move-up buyers carrying equity from a sale. The risk: a cut can also reignite buyer competition, eroding the negotiating room that today's balanced market currently offers. Act fast on pre-approvals if you expect a cut.
Scenario 2: A Hold (Hawkish but Patient)
If the Bank holds, it signals confidence that inflation is contained but the economy does not need further stimulus. Markets typically react with a small rise in bond yields as traders unwind cut bets, nudging fixed mortgage rates up slightly. For GTA sellers, a hold often preserves the status quo — the balanced market continues, inventory stays elevated, and well-priced homes still move within 21–28 days. For buyers, a hold means borrowing costs stay where they are; the advantage is that you are not competing against a rush of newly-empowered borrowers chasing the same listings. Use this window to negotiate conditions like inspection and financing.
Scenario 3: An Unexpected Hike (Unlikely but Possible)
A rate hike is the low-probability tail risk, but trade-war-driven inflation or a surprise surge in core CPI could force the Bank's hand. A hike would immediately raise variable mortgage costs and likely push five-year fixed rates above 4.6%. For the GTA, the immediate effect is a chill on buyer demand — many pre-approved buyers see their qualification shrink and pull back from offers. Sellers feel it through longer days on market and price reductions on overpriced listings. The silver lining for cash-strong buyers and investors: a hike often creates the best negotiating conditions of the cycle, with motivated sellers and reduced competition.
How a Cut Changes Brampton Affordability
Let's run the numbers on a Brampton detached home at the $1.18M average. With 20% down ($236,000), the mortgage is $944,000. At a 4.4% five-year fixed on a 30-year amortization, the monthly payment is roughly $4,715. Cut the rate to 4.15% and the payment drops to about $4,570 — a saving of $145 per month or $1,740 per year. More importantly, at the lower rate a $130,000-income household can stretch their maximum qualification higher, potentially moving a buyer from a townhome budget into detached territory. These margins matter: in Brampton's family-driven market, a rate cut often pulls move-up buyers off the fence and into offers within 30–60 days.
Fixed vs Variable: Which Wins After the Decision?
The classic dilemma intensifies around rate decisions. If you believe further cuts are coming through late 2026 and 2027, a variable rate captures every downward move immediately — your payment drops as the BOC cuts. If you prefer certainty, a fixed rate locks in today's pricing for five years, protecting you if inflation re-accelerates or trade tensions worsen. A common hybrid strategy: take a shorter fixed term (3 years) to hedge — you get stability now but renew into what many economists expect will be a lower-rate environment by 2029. Always compare the stress test (contract rate + 2%) across lenders; the difference between a bank's loyalty renewal offer and a broker-sourced competing offer is frequently 0.25%–0.5%.
What Sellers Should Do Before the Announcement
If a cut looks likely, listing just after the decision can capture the surge in buyer activity — but only if your home is priced right and market-ready. Overpriced listings still sit even in a rate-cut rally. Invest in professional photography, address deferred maintenance, and price within 2% of comparable sales from the last 30 days. If your home has a legal basement suite or rental potential, lead with it — investor demand for income-producing Brampton properties is at a multi-year high, and a rate cut makes the cash-flow math even more attractive to investors. Be ready to negotiate; balanced markets reward flexible sellers.
What Buyers Should Do Before the Announcement
First, get a rate hold or pre-approval now — most lenders guarantee today's rate for 90–120 days, so you are protected if rates rise and can often access the lower rate if they fall (ask your broker about rate-drop guarantees). Second, set up customized listing alerts for your target Brampton and GTA neighborhoods so you see new inventory the moment it hits the market. Third, gather your documents (income proof, down payment source, ID) so you can move quickly. If the BOC cuts, expect a brief flurry of competition in the 2–4 weeks after the announcement; if it holds, you retain your negotiating leverage. Either way, being pre-approved and ready is the single highest-leverage move you can make.
The Bigger Picture: Rates Are Just One Variable
While the BOC decision dominates headlines, remember that local supply and demand drive your specific transaction far more than the overnight rate. Brampton's inventory is up 18% year-over-year, days on market have stretched to 21–28 days for detached homes, and well-priced properties in top school zones still sell within two weeks. Employment stability, household income, down payment size, and the specific neighbourhood's absorption rate all matter more than a 25-point move. The buyers and sellers who win do not try to perfectly time the BOC — they act on local data with rate protection in place.
Build Your Rate-Decision Game Plan
Whether the Bank cuts, holds, or surprises the market, the right preparation turns uncertainty into opportunity. I provide every client with a customized affordability analysis at multiple rate scenarios, a neighbourhood-level market snapshot, and a clear action plan tied to the BOC calendar. Get pre-approved, set your alerts, and know your numbers before the next announcement. Book a free consultation today and let's build a mortgage and real estate strategy that holds up no matter which way rates move.